Every few months this year, a household payments name has bought its way into stablecoins rather than built its way in. Stripe bought Bridge, then Privy. Mastercard just closed on BVNK. Ripple bought Rail. Coinbase and Mastercard both chased the same target before only one of them won. The pattern is no longer a trend. It is the shape of the market.
The Deal Data Tells the Story
Crypto M&A hit a record in the first half of 2026: 87 announced acquisitions and $9.66 billion in disclosed deal value, up 223 percent from the second half of 2025, the highest half-year total on record. Four deals accounted for three-quarters of that value. DeFi acquisitions, the purely crypto-native kind, fell by more than half over the same stretch, from 24 deals to nine.
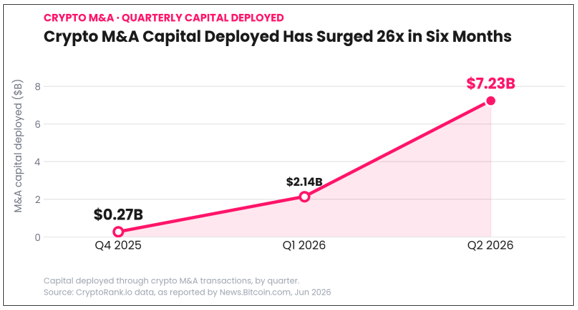
Source: Cryptotank.io
Infrastructure took the share DeFi gave up, and stablecoin infrastructure specifically supplied most of the biggest checks. That split matters. It means the money isn’t chasing speculative crypto products anymore. It is chasing the plumbing that lets a regulated financial institution move a stablecoin without touching anything that looks like a casino.
Stripe Wrote the Playbook First
Stripe saw this earliest. It paid $1.1 billion for Bridge, a stablecoin infrastructure firm, in a deal that closed in February 2025, then followed a few months later by acquiring Privy, the embedded-wallet company behind more than 75 million crypto wallet accounts. Bridge gave Stripe the rails to issue and move stablecoins. Privy gave it the interface millions of end users would touch without ever knowing a blockchain was involved.
Neither deal was about entering crypto for its own sake. Stripe processes more than a trillion dollars in payments a year, and its own leadership has said plainly that stablecoins are growing faster inside Stripe than almost anything the company has shipped before. Buying, rather than partnering, was the fastest way to own that growth curve outright.
Card Networks Followed the Money
Mastercard’s answer came a year later and cost more. It completed its $1.8 billion acquisition of BVNK on August 3, closing five months ahead of its original year-end target after clearing regulatory review faster than expected. BVNK wasn’t short of suitors. Coinbase had pursued the company at a reported valuation near $2 billion before those talks collapsed, and Mastercard had separately explored buying Zerohash before that deal also fell apart.
Visa is running the same playbook from a different angle, funding its own stablecoin settlement pilots rather than making a signature acquisition yet, and it had used BVNK itself as a pilot partner before Mastercard took the company off the market entirely. Every major card network now has to decide whether to own stablecoin infrastructure or rent it from a competitor. Mastercard just answered that question for itself.
Why the Deals Are Suddenly Easy to Approve
None of this would move this fast without the regulatory floor the GENIUS Act placed in mid-2025. Analysts covering the BVNK deal specifically credited the law, alongside the EU’s MiCA framework, with giving both sides of the transaction an explicit legal definition of stablecoin infrastructure that simplified the review. Regulatory uncertainty used to be the reason big, risk-averse acquirers stayed on the sidelines. It is now the reason they can move.
That is the real story behind the M&A numbers. A bank’s legal team cannot sign off on buying a company built on ambiguous rules. It can sign off on buying one that operates inside a federal framework with defined custody, reserve, and licensing requirements. The GENIUS Act did not just legalize stablecoins. It made them acquirable.
Convergence Runs Both Directions
It would be a mistake to read this as only TradFi buying its way into crypto. Ripple, a crypto-native company since 2012, paid $200 million for Rail, a stablecoin payments platform with more than a dozen banking partnerships, specifically to gain the regulated banking rails Rail had already built. The acquisition target in that deal looked almost identical to what Stripe bought in Bridge. The buyer just came from the other side of the industry.
That symmetry is the actual point. When a crypto-native firm and a 60-year-old card network are both spending hundreds of millions of dollars to acquire the same kind of company, the old label of “crypto versus TradFi” has stopped describing anything real. What is left is one payments industry, splitting its M&A budget on the same asset: compliant stablecoin infrastructure.
What Comes Next
Expect the pace to keep compounding rather than cool off. The 2025 GENIUS Act is the catalyst. Every deal that closes cleanly, the way BVNK’s did months ahead of schedule, makes the next one easier to underwrite.
Stablecoins didn’t just create a new product category worth building. They created the first crypto infrastructure that a public company’s board can approve buying outright, in size, without a debate about legality. That is a bigger shift than any single acquisition, and it is the reason this M&A wave has further to run.